
Affordable Auto Insurance Utah: Quality Coverage on a Budget
Utah drivers face real pressure to balance protection with cost. Insurance premiums keep climbing, and finding affordable auto insurance in Utah without sacrificing coverage quality feels impossible for many.
We at Direct Insurance Services know the frustration. That’s why we’ve put together practical strategies to help you cut your premiums while keeping the protection you need.
How to Find Affordable Auto Insurance in Utah
Compare Quotes from Multiple Insurance Companies
Shopping for auto insurance in Utah requires a strategic approach. The most effective first step involves comparing quotes across multiple carriers. Most Utah drivers stick with their current insurer out of habit, which costs them money. National data shows that drivers who compare quotes save an average of $487 annually, yet over 60% of Utah residents never request a second quote.
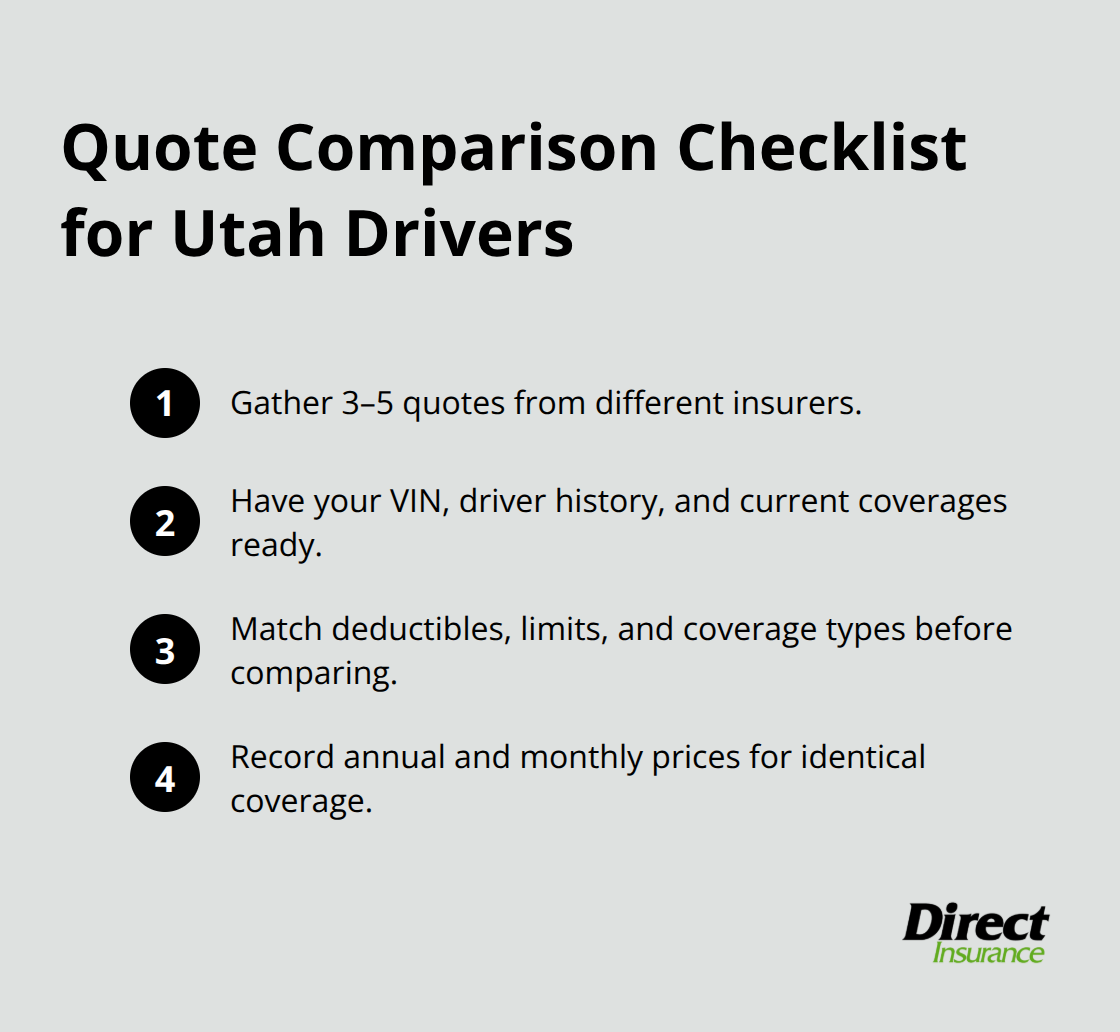
Gather quotes from at least three to five different companies. This takes roughly 15 minutes per insurer if you have your vehicle information and driving history ready. You’ll notice dramatic price variations for identical coverage, sometimes ranging from $800 to $1,400 annually for the same vehicle and driver profile. Verify that each quote includes the same deductibles, liability limits, and coverage types before comparing.
Unlock Real Savings Through Available Discounts
Insurance companies offer legitimate discounts that many Utah drivers overlook entirely. Safety feature discounts apply if your vehicle has anti-theft devices, automatic seatbelts, or advanced driver assistance systems (reducing your premium by 5% to 15%). Bundling auto insurance with home or renters coverage typically saves 15% to 25% on your auto policy alone.
Good driver discounts reward accident-free records, often worth 10% or more. Low-mileage discounts apply if you drive fewer than 7,500 miles annually, which suits many Utah residents who work locally. Ask about affiliation discounts through employers, professional organizations, or alumni associations, which can add up to 10%. These discounts stack, meaning a driver with four qualifying discounts could reduce premiums by 40% or more.
The critical mistake involves assuming you automatically receive these discounts. You must explicitly request them, and some companies don’t advertise all available options. When you request quotes, specifically ask which discounts you qualify for rather than accepting the initial quote.
Adjust Coverage Limits and Deductibles to Your Situation
Utah requires minimum liability coverage of 25/50/15, meaning $25,000 bodily injury per person, $50,000 total per accident, and $15,000 property damage. Many drivers blindly purchase these minimums, which leaves them dangerously exposed. If you cause an accident injuring multiple people, $50,000 disappears quickly with medical bills and legal fees. Raising your liability limits to 100/300/100 typically costs only $15 to $30 more monthly but provides substantially better protection.
Your deductible choice dramatically impacts your premium. Increasing from a $500 deductible to $1,000 reduces your collision and comprehensive coverage costs by approximately 15% to 20%. This strategy works only if you have emergency savings to cover that deductible. Skip collision and comprehensive coverage on vehicles worth less than $5,000, since the savings don’t justify the risk. Conversely, newer vehicles or those with outstanding loans require full coverage regardless of cost.
Calculate your vehicle’s actual value, determine what deductible you can genuinely afford if damage occurs, then structure your policy accordingly. This math matters more than general advice. Understanding these three levers-quote comparison, discount stacking, and coverage customization-positions you to move forward with confidence toward the specific rate reductions that fit your situation.
Common Factors That Affect Your Auto Insurance Rates in Utah
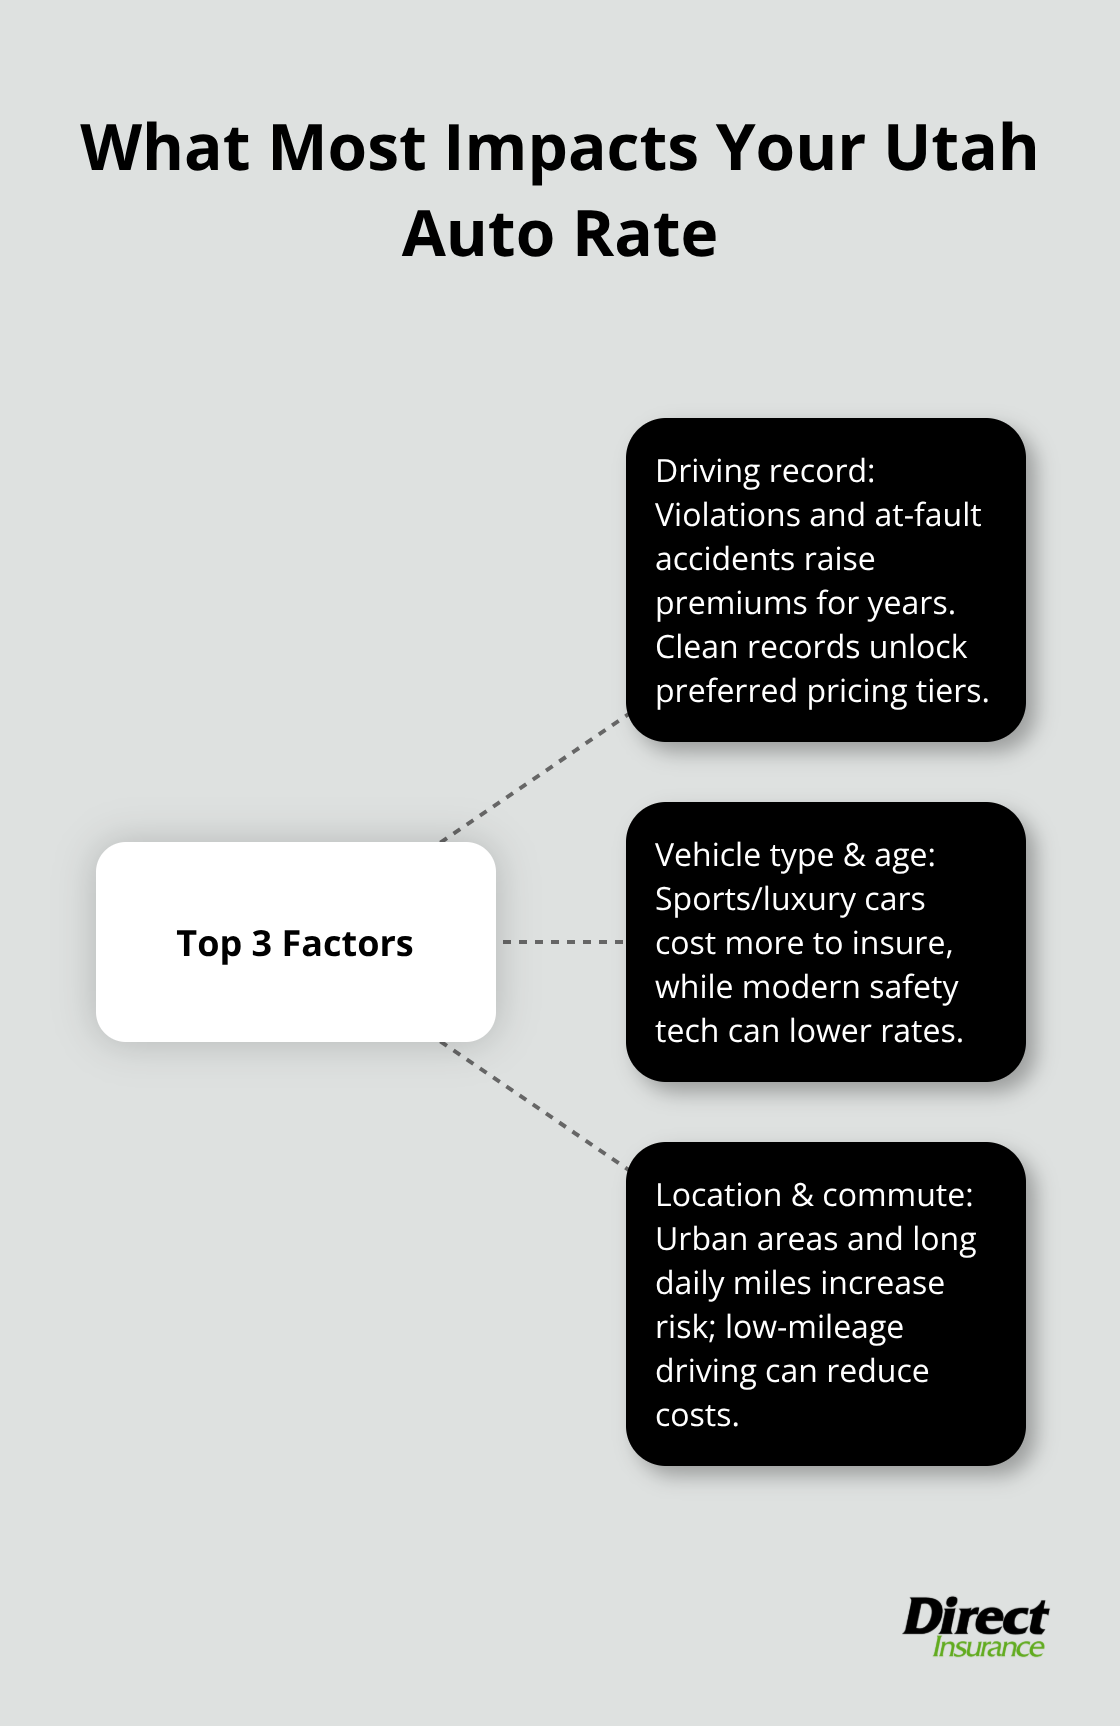
Insurance companies don’t calculate your premium randomly. Three major factors dominate your rate calculation in Utah, and understanding each one gives you real leverage to negotiate better pricing.
Your Driving Record and History
Your driving record matters most. A single at-fault accident increases your premium by approximately 25% to 40% for three to five years, while a DUI conviction can spike rates by 300% or more. Utah’s Department of Public Safety tracks all violations, and insurers pull this data automatically.
Any moving violation that shows up on your driving record may increase your car insurance rate, with the size of the increase depending on the severity of the violation. Clean records unlock the best rates, so defensive driving matters financially, not just legally. The difference between a spotless record and one with violations can easily exceed $1,000 annually across your policy lifetime.
Your Vehicle Type and Age
Your vehicle’s characteristics determine your rate more than you’d expect. Insurers charge 20% to 30% more for sports cars and luxury vehicles because repair costs and theft rates run higher. A 2024 Toyota Camry costs substantially less to insure than a 2024 Dodge Charger, even with identical coverage.
Older vehicles cost less to insure due to lower replacement costs, though vehicles over 15 years old sometimes face higher rates if they lack modern safety features. Anti-lock brakes, electronic stability control, and automatic emergency braking systems reduce your rate by 5% to 15%. These safety technologies directly impact what insurers charge you.
Your Location and Commute Distance
Your commute distance and location within Utah significantly impact pricing. Urban drivers in Salt Lake City pay roughly 15% to 25% more than rural drivers due to higher accident frequency and theft rates. Commuting 50 miles daily to work increases your rate compared to working locally, since more miles mean greater accident exposure.
If you work from home or drive under 10,000 miles annually, this becomes your strongest negotiation point for low-mileage discounts that most drivers ignore completely. These three factors-your driving history, vehicle type, and location-form the foundation of your rate. Once you understand how insurers weight each factor, you can identify which discounts and coverage adjustments will save you the most money. The next section reveals specific strategies that directly counter these rate increases.
Tips for Lowering Your Auto Insurance Premiums
Bundle Your Policies Together
Consolidating your home and auto policies with one insurer delivers the fastest way to reduce your insurance costs in Utah. Insurance companies reward this loyalty aggressively, typically offering 15% to 25% discounts on your auto policy when you add it to an existing home or renters policy. The math works because insurers prefer managing multiple policies with one customer rather than hunting for new business elsewhere.
If you currently carry home insurance through one company and auto insurance through another, you’re leaving substantial savings on the table. Contact your home insurer first and request a quote for auto coverage, then compare that bundled rate against your current auto-only premium. Many Utah drivers discover they save $200 to $400 annually just from consolidating their policies, and some see savings exceeding $500 per year depending on their coverage levels and the insurer’s appetite for bundled business.
Maintain a Clean Driving Record
Your driving record directly controls whether you qualify for the lowest rates available, making this the one factor entirely within your control. A single at-fault accident carries financial consequences that vary by type and insurer, while some insurers offer accident forgiveness programs so you won’t see a rate increase. Defensive driving matters financially because clean records unlock preferred pricing tiers that insurers reserve for their safest customers.
This isn’t about being cautious on the road; it’s about understanding that every ticket and accident decision carries a tangible financial penalty that compounds over years. If you’ve had violations in the past, focus on maintaining a spotless record going forward to age out those incidents and gradually return to standard rates. Each violation-free year moves you closer to the best available pricing your insurer offers.
Ask About Low-Mileage and Safety Feature Discounts
Drivers commuting under 7,500 miles annually qualify for low-mileage discounts worth 10% to 15% off their premiums, yet most people never mention their actual mileage to insurers. Vehicles equipped with anti-lock brakes, electronic stability control, blind-spot monitoring, or automatic emergency braking systems earn safety discounts ranging from 5% to 15%.
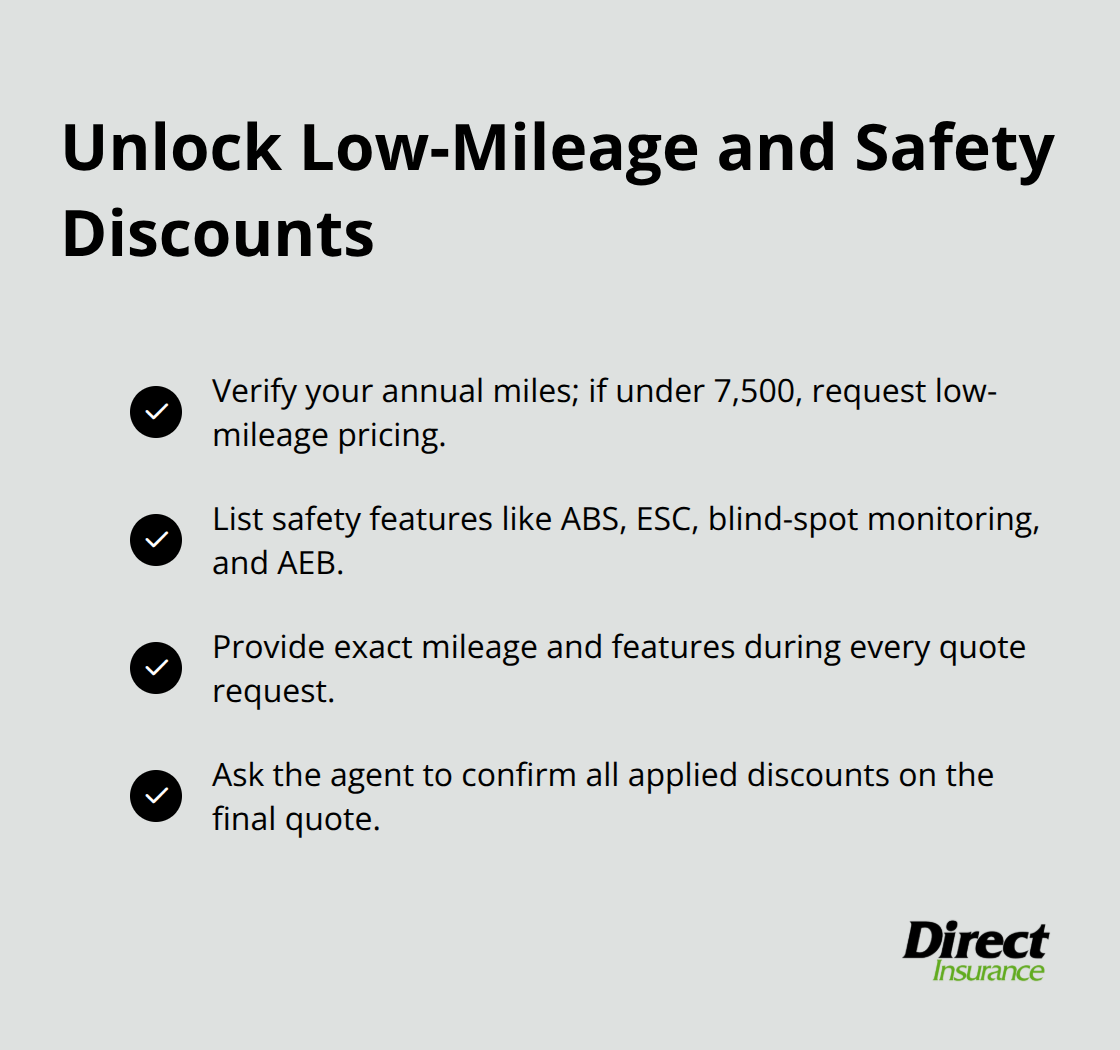
When you request quotes, provide your exact annual mileage and specifically ask which safety features your vehicle has that qualify for discounts.
These details shift your final rate significantly, and insurers won’t volunteer this information unless you ask directly. If you work from home or drive locally, this becomes your strongest negotiation point for discounts that most drivers ignore completely. The combination of low-mileage status and modern safety features can reduce your premium substantially when you mention both factors during the quote process.
Final Thoughts
You now have concrete strategies to find affordable auto insurance in Utah without sacrificing coverage quality. Comparing quotes across multiple carriers, stacking available discounts, and adjusting your deductibles based on your actual financial situation form the foundation of smart insurance shopping. Your driving record, vehicle type, and location determine your baseline rate, but these three levers give you direct control over what you ultimately pay.
Bundling your policies, maintaining a clean driving record, and mentioning low-mileage or safety feature status during quotes compound these savings significantly. Many Utah drivers reduce their premiums by $400 to $800 annually simply by implementing these tactics, yet most never take action because insurance feels overwhelming. Working with a local Utah insurance agent changes the equation entirely.
We at Direct Insurance Services have served Utah families and businesses since 1973, and we understand the specific risks and needs that come with living here. Our team shops top-rated carriers on your behalf to find the coverage that fits your budget and protects your situation, handling the quote comparison, discount verification, and coverage customization so you don’t have to spend hours navigating multiple insurance companies alone. Contact us today to discuss your current coverage and get quotes that reflect your actual driving habits, vehicle details, and location.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation

