
Personal Umbrella Coverage Utah: Protecting Your Finances From Unforeseen Events
Your homeowners and auto insurance policies have limits. When someone sues you for more than those limits cover, your personal assets are at risk.
Personal umbrella coverage in Utah fills that gap. At Direct Insurance Services, we’ve seen how quickly a single accident or lawsuit can threaten years of financial progress. This guide walks you through what umbrella coverage actually does, how much you need, and why it matters for Utah families.
What Personal Umbrella Coverage Actually Covers
Personal umbrella coverage sits on top of your existing homeowners and auto insurance policies, kicking in when claims exceed those underlying limits. Most umbrella policies start at 1 million dollars in coverage, though you can purchase 2 million, 3 million, or higher depending on your situation. The cost remains surprisingly affordable-typically ranging from 150 to 300 dollars annually for 1 million dollars of coverage. This coverage protects your personal assets if someone sues you for damages beyond what your standard policies cover, including medical expenses, lost wages, pain and suffering, and legal defense costs.
Why Your Current Policies Leave You Exposed
Standard homeowners insurance in Utah typically covers 100,000 to 300,000 dollars in liability. Auto insurance liability limits often sit at 25,000 to 100,000 dollars per person. These numbers sound substantial until a serious accident happens. A single at-fault car accident resulting in severe injuries can generate medical bills exceeding 500,000 dollars within weeks. A swimming pool incident or dog bite on your property can trigger lawsuits claiming 1 million dollars or more. When the judgment exceeds your policy limits, creditors pursue your bank accounts, investment accounts, and future wages. Utah residents with homes, vehicles, and savings face real exposure to asset seizure without adequate umbrella protection.
Real Situations Where Umbrella Coverage Prevents Financial Disaster
A homeowner’s teenage child causes a car accident injuring multiple people. The medical bills total 750,000 dollars, but the auto policy covers only 100,000 dollars. The injured parties sue for 900,000 dollars total. The umbrella policy covers the 800,000 dollar gap, protecting the family’s home and retirement accounts.
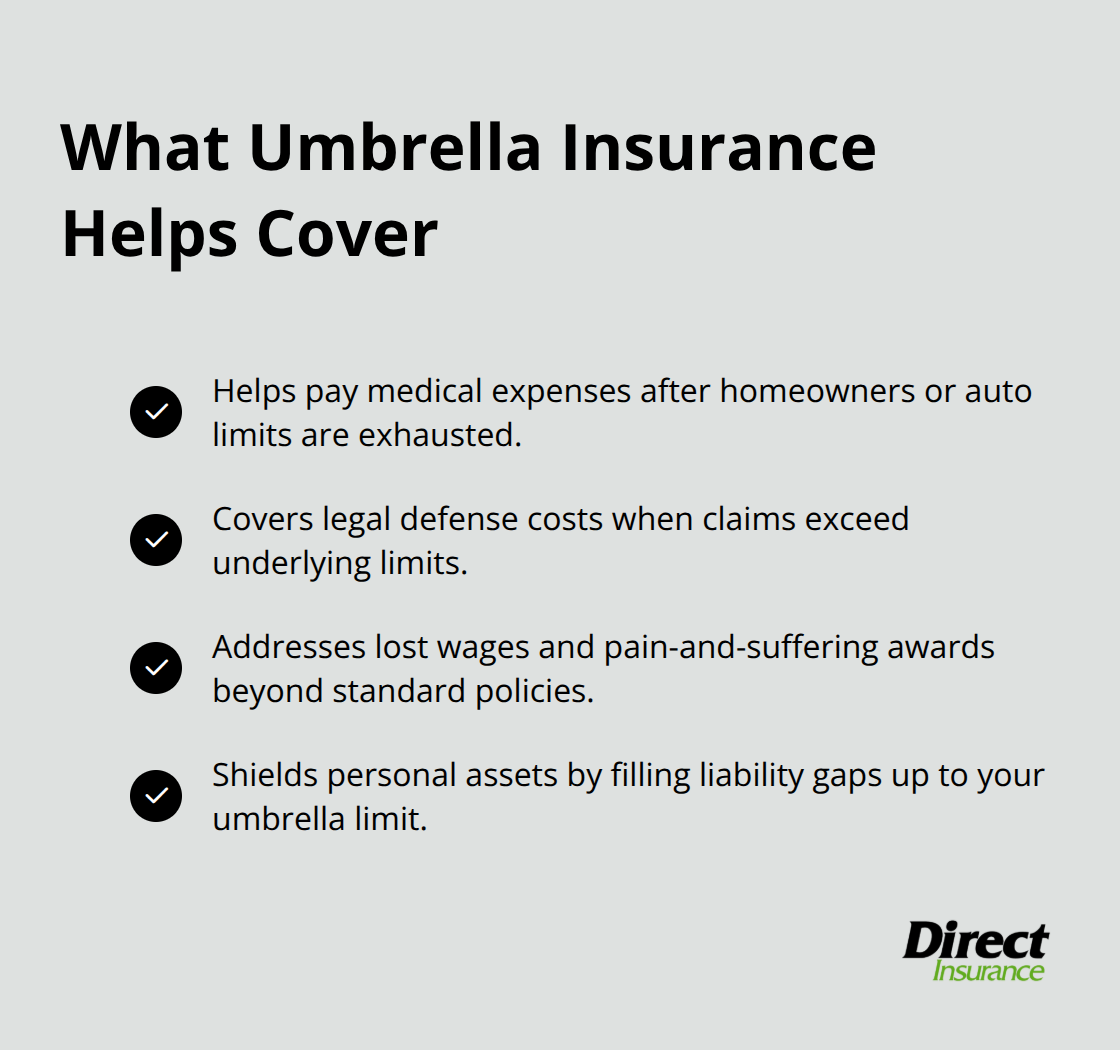
Another scenario involves a guest slipping on ice in your driveway during winter. The resulting spinal injury requires surgery and ongoing physical therapy costing 600,000 dollars. Your homeowners policy covers 300,000 dollars. The umbrella policy protects you from the 300,000 dollar shortfall. These situations reflect outcomes that impact Utah families without proper coverage.
How Much Coverage Actually Costs
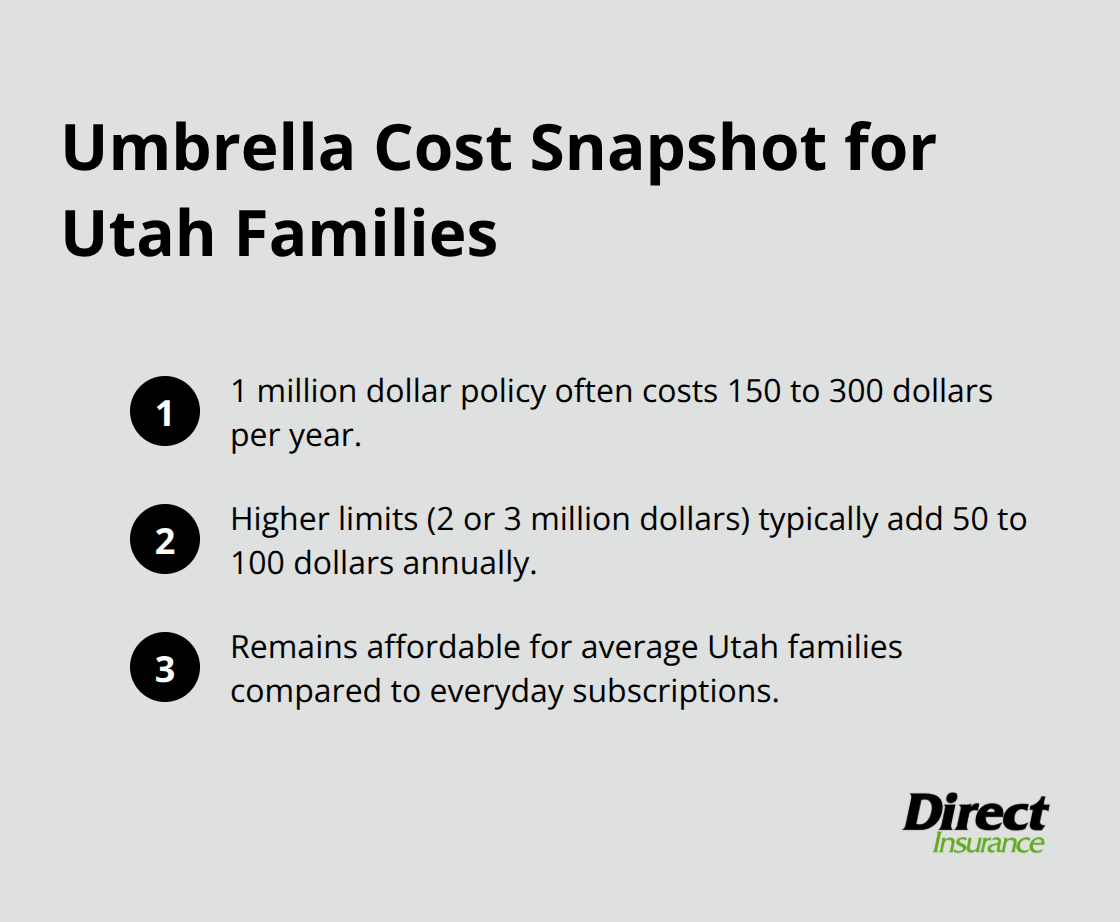
The affordability of umbrella insurance surprises most people. A 1 million dollar policy typically costs between 150 and 300 dollars per year for homeowners and auto policyholders. Higher limits (2 or 3 million dollars) add minimal cost-often just 50 to 100 dollars more annually. This low price point makes umbrella coverage accessible to average Utah families, not just the wealthy. The investment protects far more than its annual cost.
What Happens When You Need It Most
Umbrella coverage activates only after your underlying policies reach their limits. Your homeowners and auto policies pay first, then the umbrella policy covers the remainder up to your chosen limit. This layered approach means you maintain your existing coverage while adding a financial safety net. Without this protection, a single lawsuit can wipe out decades of savings and future income.
Now that you understand what umbrella coverage protects and why standard policies fall short, the next critical question becomes: how much coverage do you actually need for your specific situation?
How Much Coverage Do You Need
Calculate Your Net Worth First
Your financial exposure determines the coverage amount you need, not industry standards or what neighbors carry. Start by calculating your net worth accurately. Add up your home value, vehicles, investment accounts, retirement savings, and any other assets. If you own a home worth 400,000 dollars and have 150,000 dollars in savings and investments, your net worth totals 550,000 dollars. This number represents what creditors can pursue if a lawsuit exceeds your underlying policy limits.
Account for Future Earning Potential
Most financial advisors recommend umbrella coverage equal to your total assets and potential future income. However, Utah residents with significant earning potential should consider coverage that also protects future income. Someone earning 75,000 dollars annually has 20-25 years of potential income ahead, which means coverage of 1 million to 2 million dollars makes more sense than a 500,000 dollar policy. Your future wages matter as much as your current assets when calculating adequate protection.
Understand Utah-Specific Risk Factors
Utah’s property values vary dramatically by location. Salt Lake City residents in neighborhoods averaging 600,000 to 800,000 dollars per home need higher limits than those in rural areas. If you own a pool, trampoline, or frequently host guests, your liability exposure increases substantially. A guest drowning in your pool or suffering a serious trampoline injury can generate lawsuits exceeding 2 million dollars, particularly if the injury involves a child.
Winter weather creates additional liability exposure unique to Utah. Ice and snow on driveways generate slip-and-fall hazards that produce significant injury claims. Outdoor recreation activities common to Utah residents (such as hosting group activities or operating recreational vehicles) elevate your risk profile.
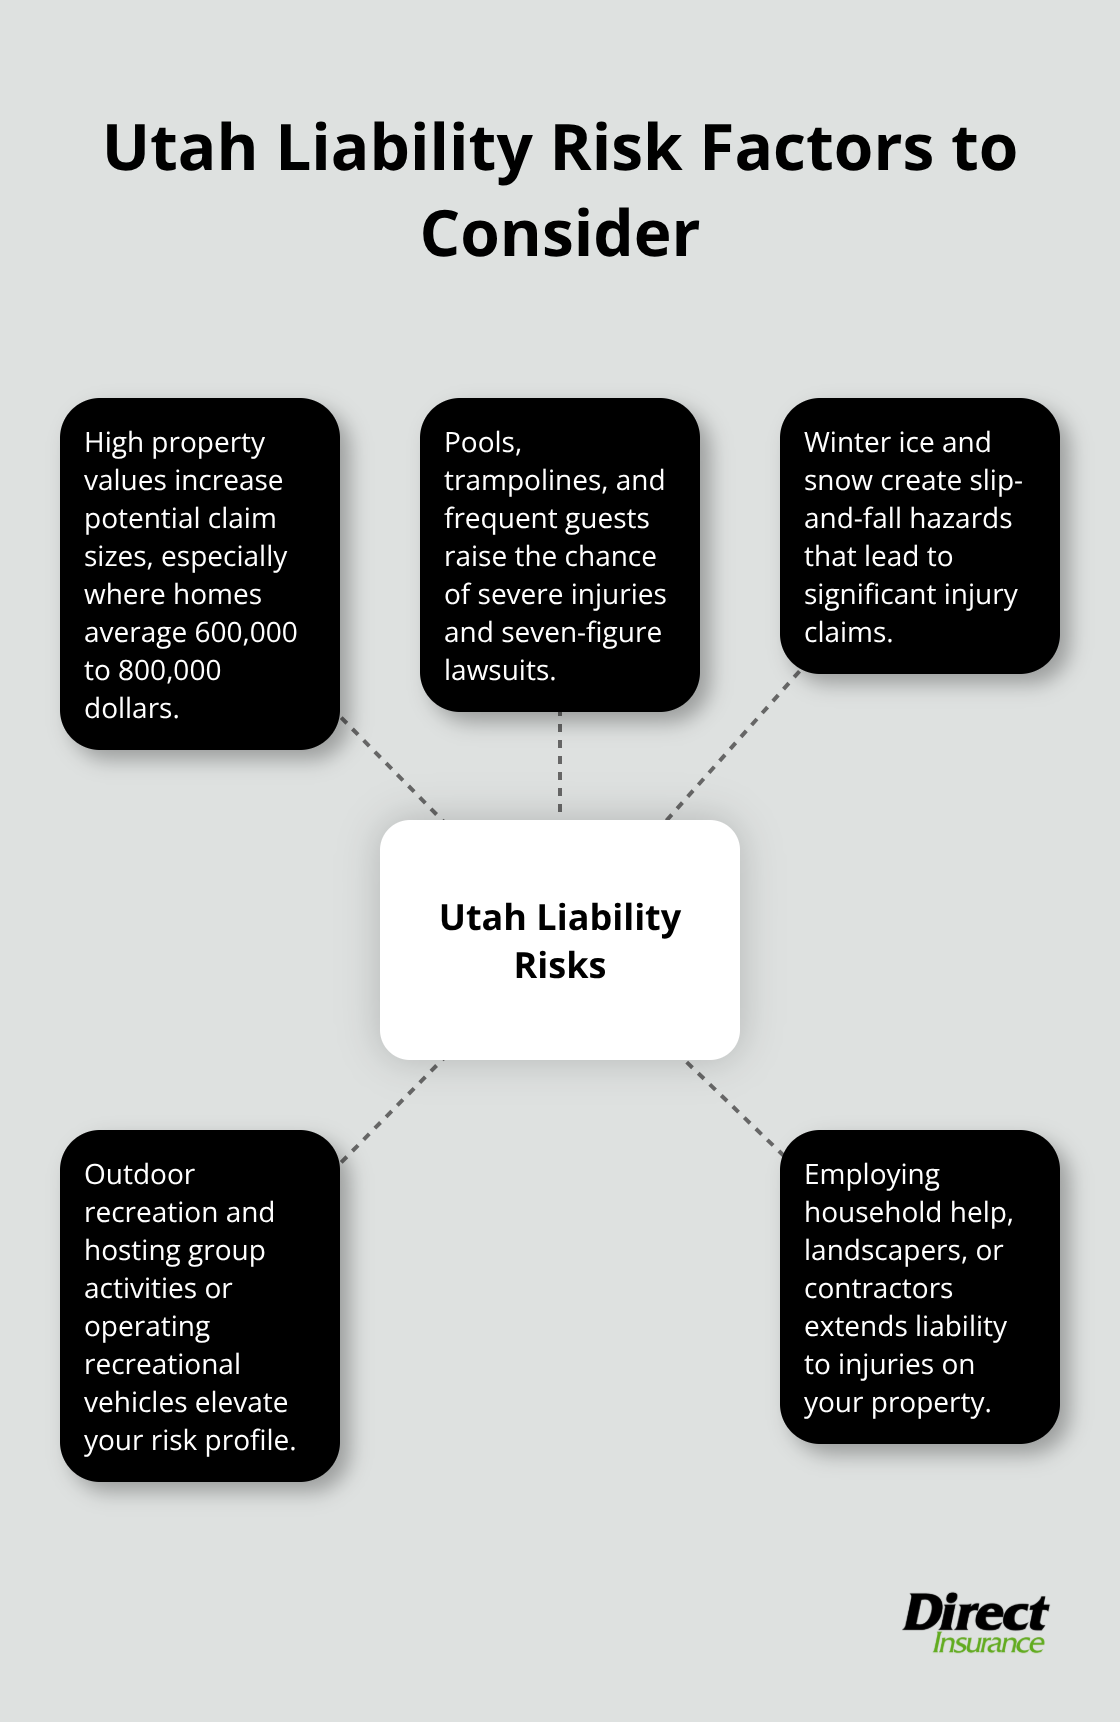
If you employ household help, landscapers, or contractors regularly, your liability extends to their potential injuries on your property.
Select Coverage Limits That Match Your Situation
Most homeowners and auto policyholders can adequately protect themselves with 1 million dollars of umbrella coverage for approximately 150 to 250 dollars annually. This assumes relatively modest net worth and limited high-risk activities. Families with homes valued above 600,000 dollars, multiple vehicles, or rental properties should seriously consider 2 million dollars of coverage. The additional cost rarely exceeds 75 to 100 dollars per year, making it a practical upgrade rather than an extravagance.
Higher limits (2 or 3 million dollars) add minimal cost to your annual premium. This low price point makes umbrella coverage accessible to average Utah families. The investment protects far more than its annual cost. Once you understand your coverage needs, misconceptions about umbrella insurance often prevent families from taking action-and those myths deserve examination.
Common Misconceptions About Personal Umbrella Insurance
Umbrella Coverage Only Protects Against Major Disasters
Most people believe umbrella coverage activates exclusively for catastrophic accidents or major lawsuits, which fundamentally misunderstands how this protection works. The reality spans far broader situations. Umbrella policies cover everyday liability claims that exceed your standard homeowners and auto limits, not just worst-case scenarios. A guest suffering a minor injury on your property that requires emergency surgery, a minor fender-bender that injures someone in the other vehicle, or a dog bite requiring reconstructive surgery all trigger umbrella coverage if medical bills climb past your underlying policy limits.
These situations happen more frequently than most people realize. The National Safety Council reports that unintentional injuries cost Americans over 4.7 trillion dollars annually, and many of these claims originate from ordinary incidents on residential properties or during routine driving. Your umbrella policy protects you regardless of whether the incident made headlines or barely made the local news.
Umbrella Coverage Costs Too Much for Average Families
The second major myth claims umbrella coverage is prohibitively expensive for average families, yet the numbers tell a completely different story. Utah families earning typical middle-class incomes protect themselves with 1 million dollars of coverage for 150 to 250 dollars per year, which costs less than most people spend on streaming subscriptions. This modest investment shields your financial future from liability claims that standard policies cannot cover.
The affordability of umbrella insurance surprises most people when they actually obtain quotes. A 1 million dollar policy typically costs between 150 and 300 dollars annually for homeowners and auto policyholders. Higher limits (2 or 3 million dollars) add minimal cost-often just 50 to 100 dollars more annually. This low price point makes umbrella coverage accessible to average Utah families, not just the wealthy.
Your Current Policies Already Provide Enough Protection
The third misconception suggests that your homeowners and auto insurance already provide sufficient protection, but this ignores the documented gap between standard policy limits and actual injury costs. A single serious accident generates medical bills, lost wages, pain and suffering claims, and legal fees totaling 750,000 to 1.5 million dollars, while your standard policies cover only 100,000 to 300,000 dollars. Without umbrella coverage, you personally pay the difference from your bank accounts, investment accounts, and future wages.
Utah residents who delay purchasing umbrella protection because they believe these myths expose their families to financial devastation that a modest annual premium could easily prevent. Standard homeowners insurance in Utah typically covers 100,000 to 300,000 dollars in liability, while auto insurance liability limits often sit at 25,000 to 100,000 dollars per person. These numbers sound substantial until a serious accident happens and medical bills exceed 500,000 dollars within weeks.
Final Thoughts
Personal umbrella coverage in Utah protects your financial future when accidents exceed what your standard policies cover. A single serious injury claim costs 750,000 dollars or more, while your homeowners and auto policies typically cover only 100,000 to 300,000 dollars combined. Without umbrella protection, creditors pursue your savings, investments, and future wages-with it, you pay roughly 150 to 300 dollars annually for 1 million dollars of coverage.
Your net worth and Utah-specific risks determine how much coverage you actually need. Someone with a 400,000 dollar home, significant savings, and a pool or trampoline should seriously consider 1 to 2 million dollars of protection. The cost difference between these limits remains minimal, typically just 50 to 100 dollars more per year, making personal umbrella coverage Utah families can actually afford.
Contact Direct Insurance Services for a quote on personal umbrella coverage that fits your situation. Our team will calculate your actual exposure, explain your options clearly, and show you exactly what this protection costs. Most families discover they can afford comprehensive umbrella coverage without straining their budgets.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation

